Does this deal work at this price?
Scored, stress-tested, and built on comparables that were opened and read.
From 1 credit · No credit card
- 01Executive summary
- 02Location & micro-market
- 03Property & building
- 04Renovation & value-add (if planned)
- 05Pricing vs. market
- 06Rental & yield outlook
- 07Legal, ownership & tax
- 08Supply, demand & macro
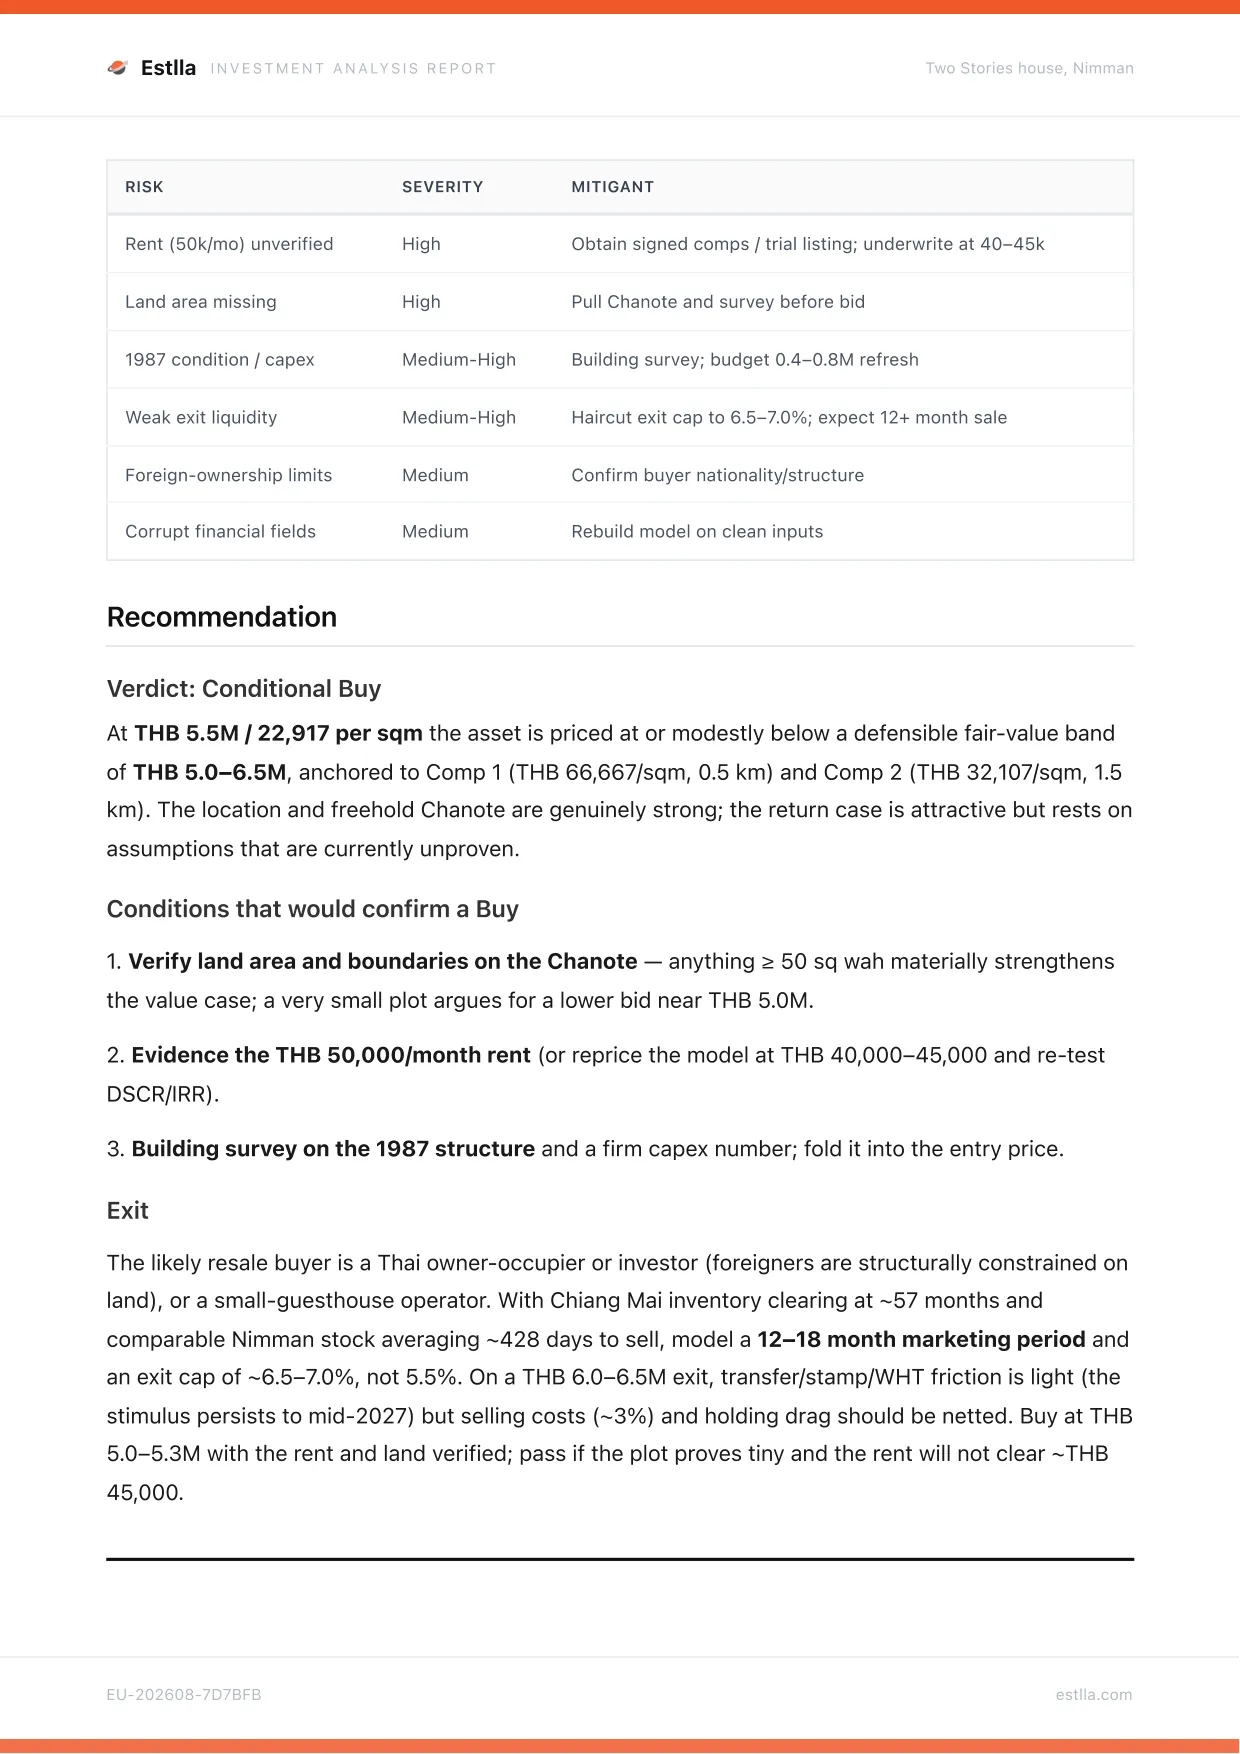
- 09Risk register
- 10Recommendation
Property in, memo out, about two minutes
The arithmetic is done for you. The judgement stays yours.
- 01
Add the property
Paste a listing link or type the address, price and size. Anything you leave blank the analysis will flag rather than quietly guess.
- 02
Set your money
Deposit, loan terms, hold period and exit assumptions. These are what make it your underwriting rather than a generic yield calculation.
- 03
Run it, then argue with it
Atlas researches the market, verifies each comparable against its live listing and writes the memo. Move any assumption afterwards and every figure follows.
No card required to start. Nothing is charged until you run an analysis.
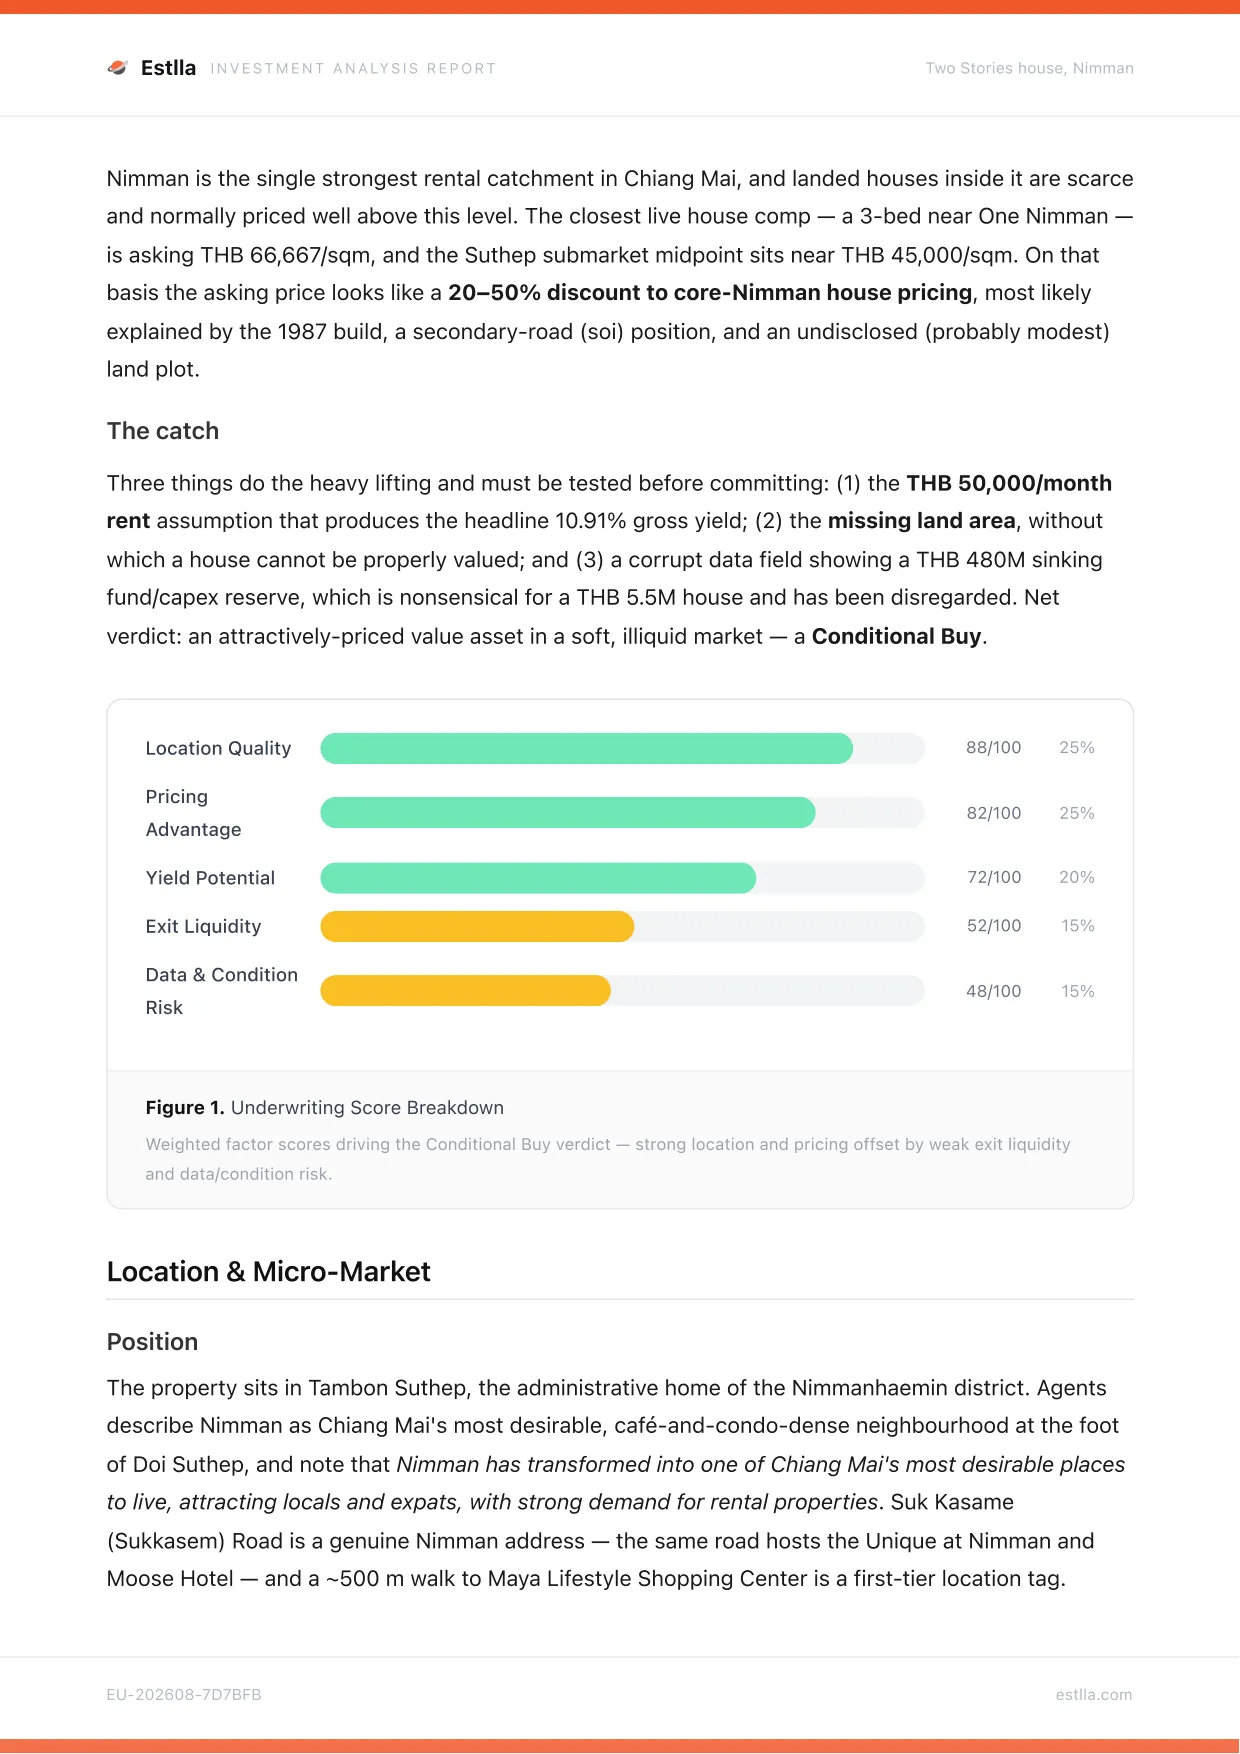
Sample analysis. Every input (rent, vacancy, costs, loan terms, exit yield) is yours, and the whole model recomputes when you move one.
Arithmetic, not opinion
Every figure is computed from your leverage and hold period before the model writes a word. Run the same deal twice and you get the same answer.
- Every figure traces to an input you can see and change
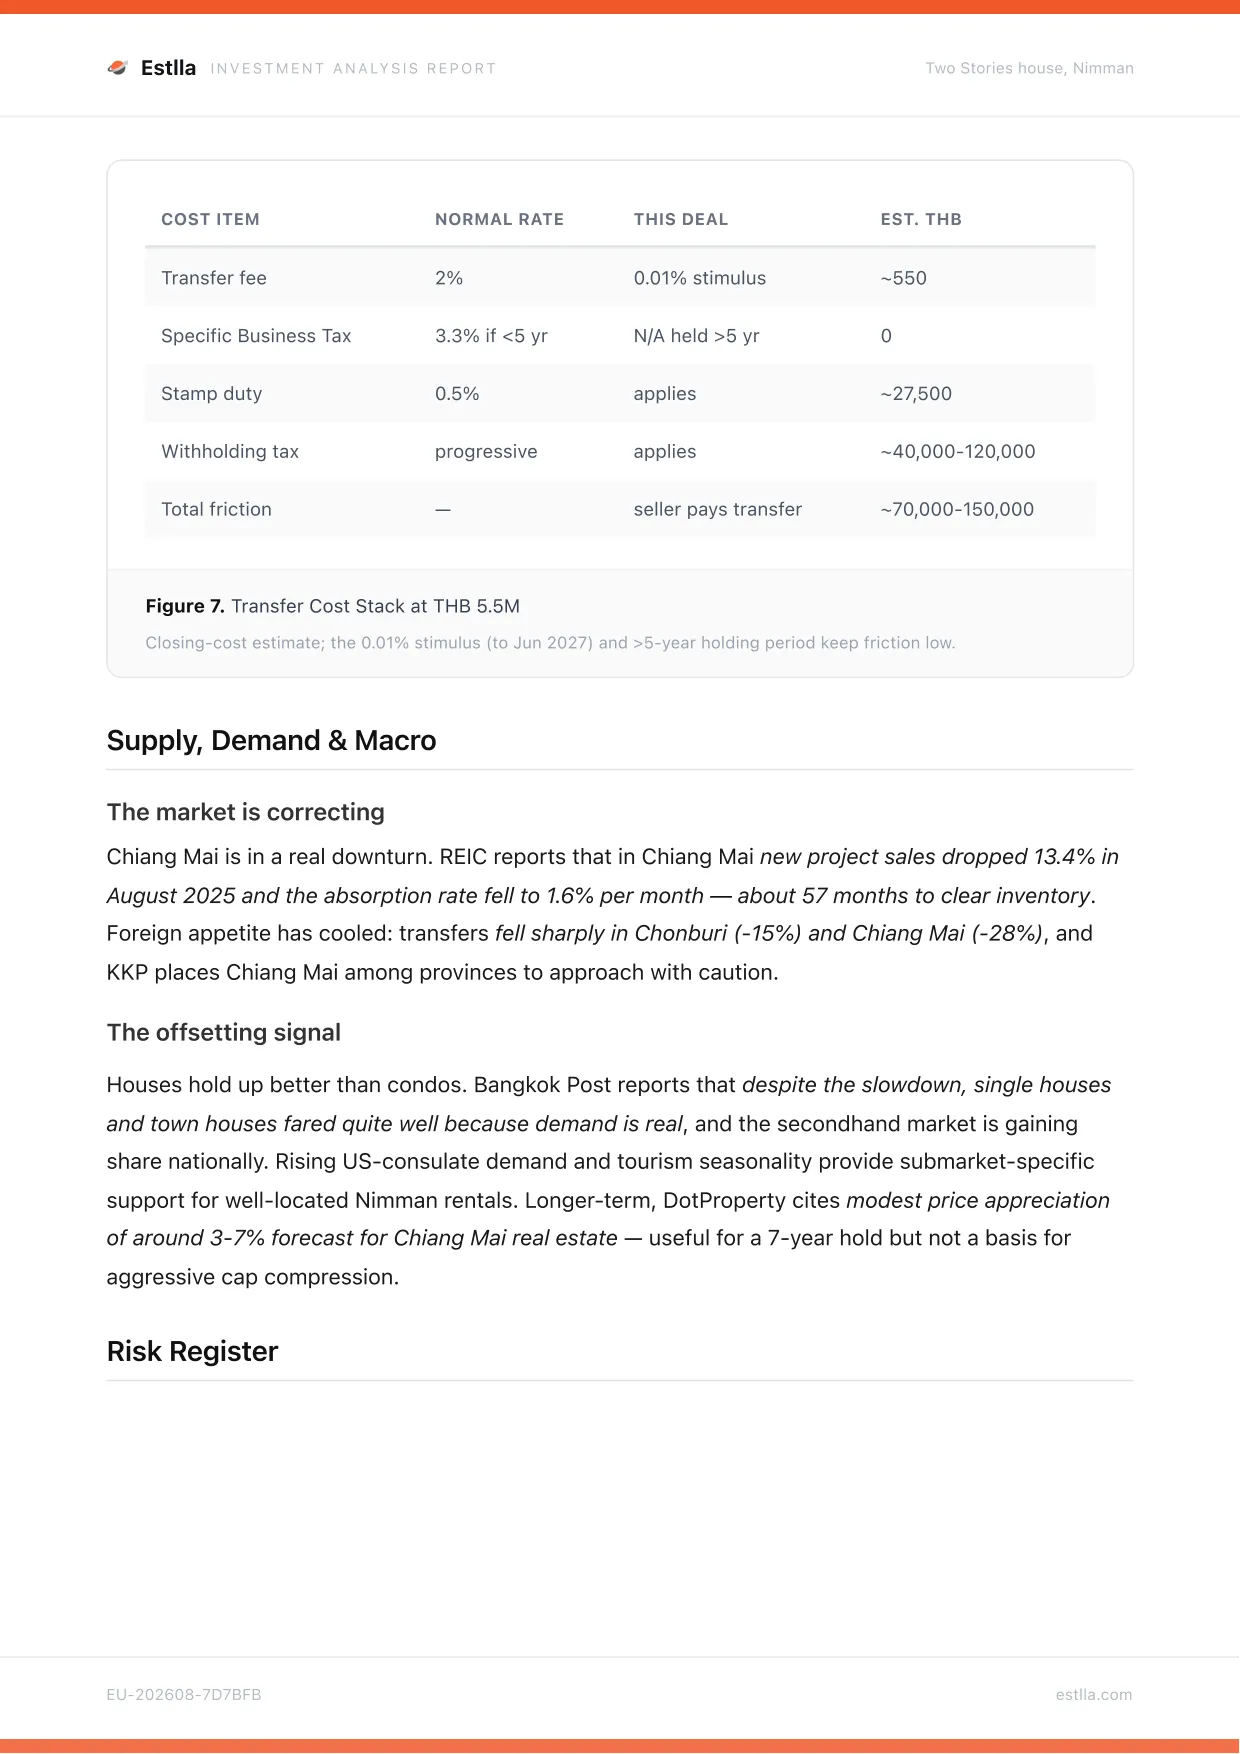
- Thai transfer costs and taxes are in the cashflow, not a footnote
- Scenarios run against the same model, not a separate estimate
An investment memo, not a score card
Ten sections, every market figure attributed, and a recommendation that takes a position.
A score and a verdict
Every memo ends with Buy, Conditional or Pass, a fair-value range, and the two or three negotiation points that would change the answer. An analysis that will not commit is not much use.
Thai law, tax and transfer costs
Title deed grade and what it means for a mortgage, the Treasury Department appraised value, the transfer-cost stack a sale actually incurs, and the ownership route open to a foreign buyer.
An analyst you can question
Disagree with a rent assumption? Change it and the whole model moves. Ask why a comparable was used and it will tell you which page it read.
The number that matters is the one after it breaks
A headline yield means little if two rate hikes sink it. This shows where cover runs out.
As underwritten
Still services debt
Thin cover
Below 1.0, needs reserve
Sample analysis. Every assumption is yours to change, and the model recomputes as you move it.
The comparables are real. We check.
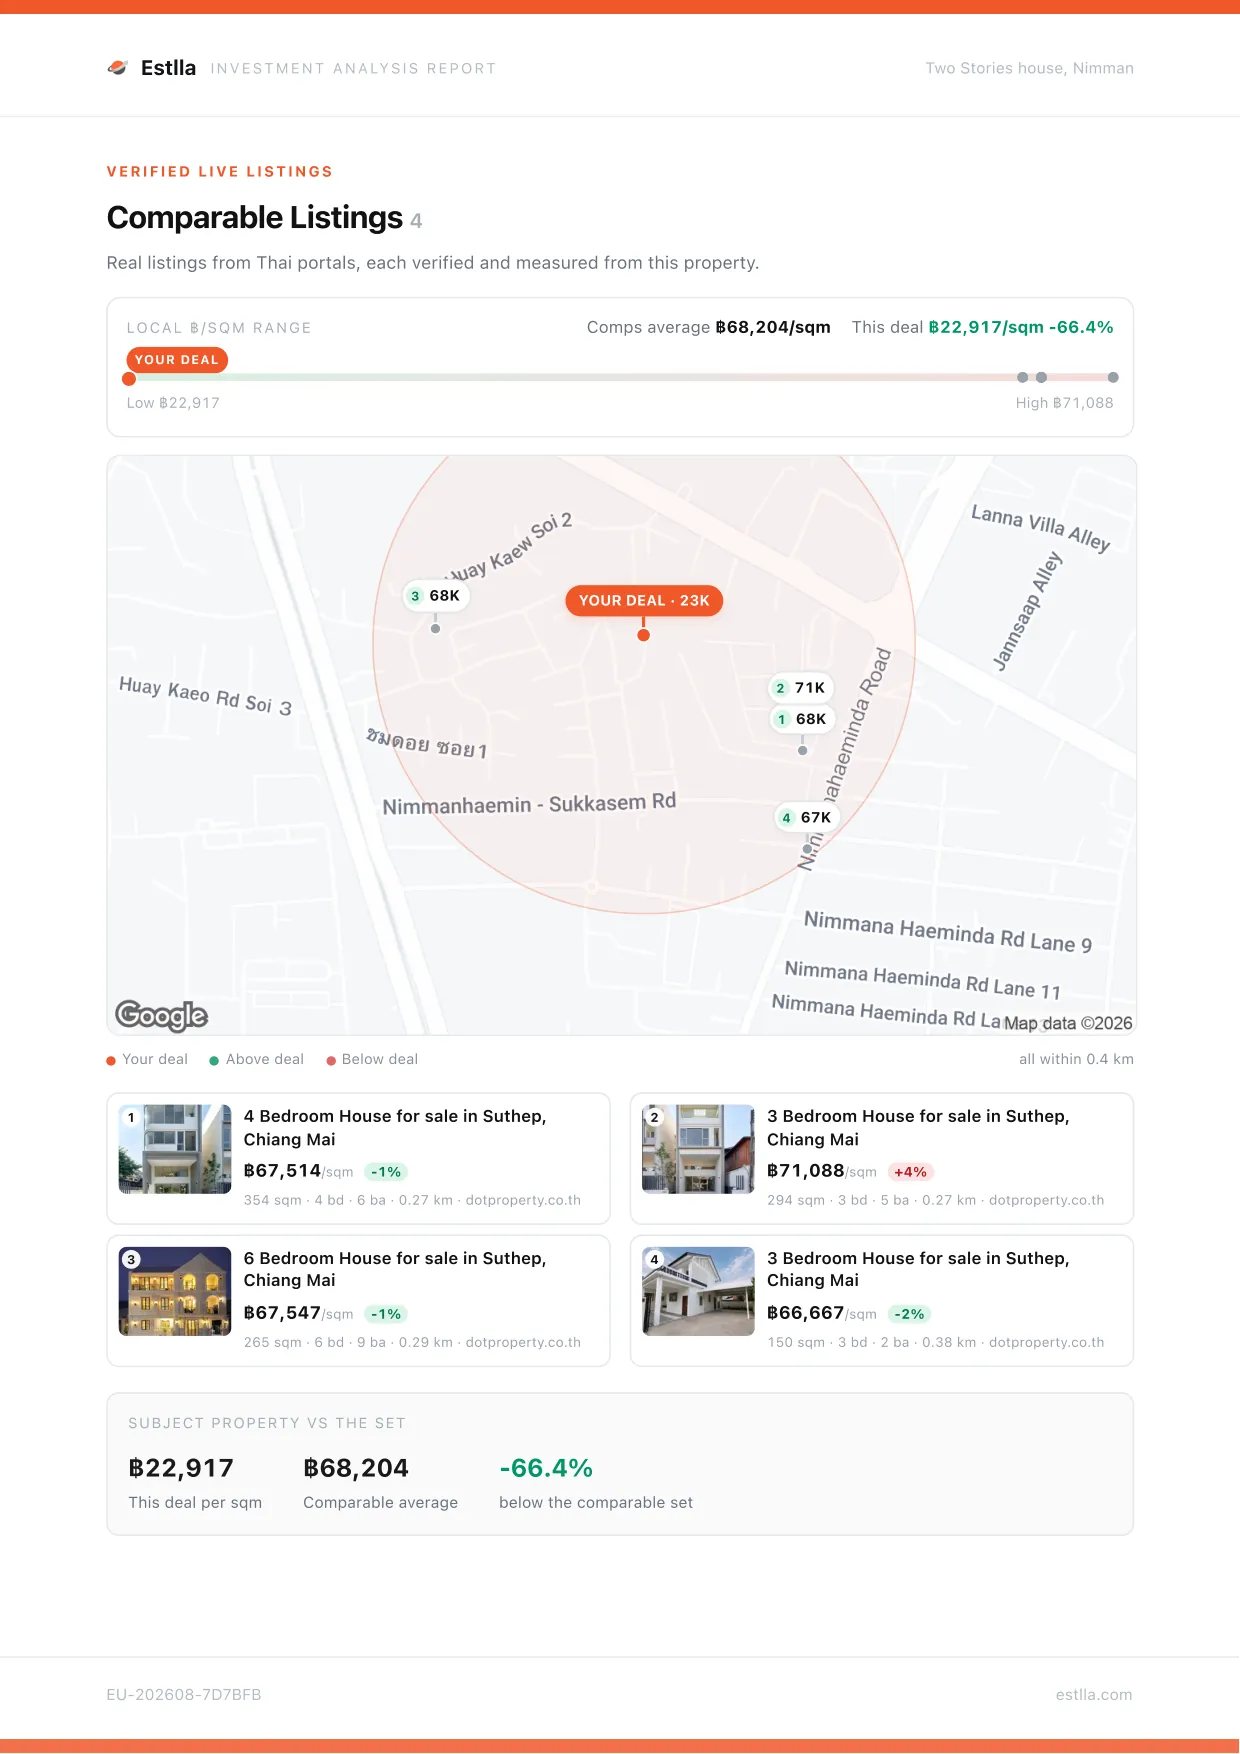
Every comparable is re-read on the page behind its link, so the card and the listing agree.
- Opens the actual listing page for every comparable
- Reads price and size off that page, not from memory
- Measures true distance from your deal, street by street
- Drops anything it cannot confirm, even if that means fewer comps

Every comparable, plotted and priced
Each pin is a listing Atlas opened, read and measured from your deal. Hover one.
Pay per analysis, not per seat
A fast scored take on whether the deal is worth a closer look. Under a minute.
The full ten-section memo with verified comparables and cited sources. About two minutes.
Reads more sources and reasons over them for longer, for a deal worth the extra minutes.
Credits come with every plan, including the free one, and do not expire within your billing period. A property can be re-analysed as often as you like. You are charged for the run, not the property.
Frequently asked questions
A transparent model, not the AI. IRR, cash-on-cash, DSCR, break-even occupancy and the year-by-year cashflow are computed from your leverage, hold period and exit assumptions. The model writes the analysis around those figures; it never produces them.
That is the point of it. Rent, vacancy, operating costs, loan terms, growth and exit yield are all yours to set, and every figure in the memo recomputes when you move one. If you disagree with an assumption, the disagreement is a number you can change rather than an argument with a chatbot.
Every one is fetched from a live Thai portal and re-read on the page behind the link before it reaches your report. If a listing cannot be opened, or its price and size cannot be confirmed, it is dropped rather than shown. You will sometimes see fewer comparables as a result; you will not see invented ones.
A quick read costs 1 credit and returns in under a minute. A researched memo costs 2 and takes about two minutes. The deepest pass, which reads more sources and reasons over them for longer, costs 15 and can take several minutes.
Yes. Every memo covers the title deed grade and what it means for a mortgage, the Treasury Department appraised value, the transfer costs a sale actually incurs, and the ownership route open to a foreign buyer: freehold within the condominium quota, leasehold, or a Thai company.
No. Estlla is analytical tooling that helps you underwrite and stress-test deals faster. It is not personalised investment advice, and it does not replace your own due diligence or a professional you pay for judgement.
Not sure the asking price is fair?
Whether a price works for you is a different question from whether it is right.